How Much Should I Have in an Emergency Fund? A Sizing Guide for Your Situation
TL;DR
Written by KeenPurse Editorial Team · Published August 20, 2026
How much should I have in an emergency fund is a sizing question, and the conventional answer is a range, not a single number: roughly three to six months of your *essential* expenses, adjusted for your own situation.
The US consumer-protection authority that publishes emergency-fund guidance says the amount you need depends on your situation, and the UK authority frames three to six months’ essential outgoings as a rule of thumb — not a regulator mandate, and not something any source can promise for everyone.
Your actual target depends on your fixed costs, income stability, household structure, dependents, and insurance deductibles. This article shows you how to estimate a defensible range for *your* life, not a guaranteed dollar figure.
The plan for actually accumulating the money lives in a separate article — how to build an emergency fund in 90 days — which this article links to rather than re-teaching. In practice, how much should I have in an emergency fund depends on the risks this plan needs to cover.
Key Takeaways
- The 3-to-6-months-of-essential-expenses figure is a rule of thumb, not a guaranteed or one-size-fits-all number.
- “Essential expenses” are the costs you cannot drop quickly (housing, food, core utilities, minimum debt payments, insurance) — not your full lifestyle outlay. Compute your own baseline rather than copying a neighbor’s.
- Your target sits inside a range that you size by your situation: fixed costs, single vs. dual income, variable or contract income, dependents, and insurance deductibles.
- The emergency fund is a reserve for unplanned shocks — distinct from a sinking fund, which holds money for expected, dated expenses.
- Where you hold it matters: a liquid, separate, easily accessible account — not invested in the market — is the usual choice (high-yield savings accounts, international).
- This article answers *how much*. The *how to actually build it* plan is the sibling article how to build an emergency fund in 90 days.
What the “3 to 6 months” rule actually is
The most common answer to “how much should I have in an emergency fund” is a period of time — three to six months of expenses — rather than an absolute amount, because an absolute figure could never fit everyone.
The UK authority puts it plainly: a good rule of thumb for a solid financial cushion is three to six months’ essential outgoings held in an instant-access savings account.
The US consumer-protection authority describes an emergency fund as a cash reserve set aside for unplanned expenses — car repairs, home repairs, medical bills, or a loss of income — so “months” is really about covering an income gap or a large unexpected bill.
Use this step to decide how much should I have in an emergency fund for your own next period.
Two things are worth being precise about, because a lot of advice blurs them: That keeps how much should I have in an emergency fund tied to your actual essentials, not a generic promise.
- **”Months” always refers to *essential* expenses, not your full spending.** The number is far smaller if you exclude discretionary spending you could pause.
- The range is a starting convention, not a rule anyone can guarantee. Both authorities emphasize that the right amount depends on your situation and that even a small start provides security — they do not name a single universal figure.
For example, the CFPB’s essential guide explains that the amount you need depends on your situation, and that if you live paycheck to paycheck even a small amount can provide some financial security. That is the correct spirit: size it to yourself. Revisit how much should I have in an emergency fund whenever your costs or income stability changes.
The right first step: count your essential expenses
Before you can estimate a multiple of months, you need a realistic number for your monthly essential spending — the number the “months” multiply against, so getting it roughly right matters more than any rule. The useful question is how much should I have in an emergency fund before the next unplanned expense.
A simple way to build it: In practice, how much should I have in an emergency fund depends on the risks this plan needs to cover.
- List the bills and needs you could not quickly eliminate: rent or mortgage, groceries, core utilities (electricity, water, heat, essential phone/internet), transport to work, minimum payments on debts, insurance premiums, and essential health costs.
- Set aside costs you *could* pause or shrink in an emergency: subscriptions, dining out, entertainment, most discretionary shopping.
- Sum only the essentials to get your essential monthly baseline.
This is arithmetic, not a promise — if your essentials are, say, 2,000 of your currency a month, then three months sits at a figure three times larger and six months at a figure six times larger. Those are *illustrative* arithmetic on numbers you supply, never a recommended amount for your life.
The honest version of the rule is: three to six times your own essential baseline, then adjust for the factors below — the same relationship the UK authority illustrates with its “three to six months’ essential outgoings” example. Use this step to decide how much should I have in an emergency fund for your own next period.
How much by situation: a sizing table
The table below turns the fuzzy rule into a range you can reason about. Every row is a range, not a single guaranteed number — your multiple falls somewhere in it depending on the rest of your situation. That keeps how much should I have in an emergency fund tied to your actual essentials, not a generic promise.
| Your situation | What it pushes toward | Typical thinking on the multiple |
|---|---|---|
| High fixed costs (large rent/mortgage, big loan payments, car you rely on) | The “months” part of the math multiplies a larger number | Your target is likely in the higher part of the range because the same income gap costs more to cover |
| Single income, sole earner | Higher multiple | One income stream means no second salary to fall back on; many aim toward the upper end |
| Dual income | Lower-to-middle multiple | Two streams can soften a single job loss, though both can be affected in a downturn |
| Variable / contract / commission income | Higher multiple | Irregular income means you may need a larger buffer to smooth months where pay is thin or absent |
| Dependents (children, parents, others you support) | Higher multiple | More people depend on the fund for essentials |
| Large insurance deductibles / big co-pays | Higher multiple | A health, home, or auto claim could mean a large out-of-pocket bill before coverage steps in |
| Small deductibles, low fixed costs, stable salary | Lower-to-middle multiple | Fewer large shocks to fund means a smaller reserve can be defensible |
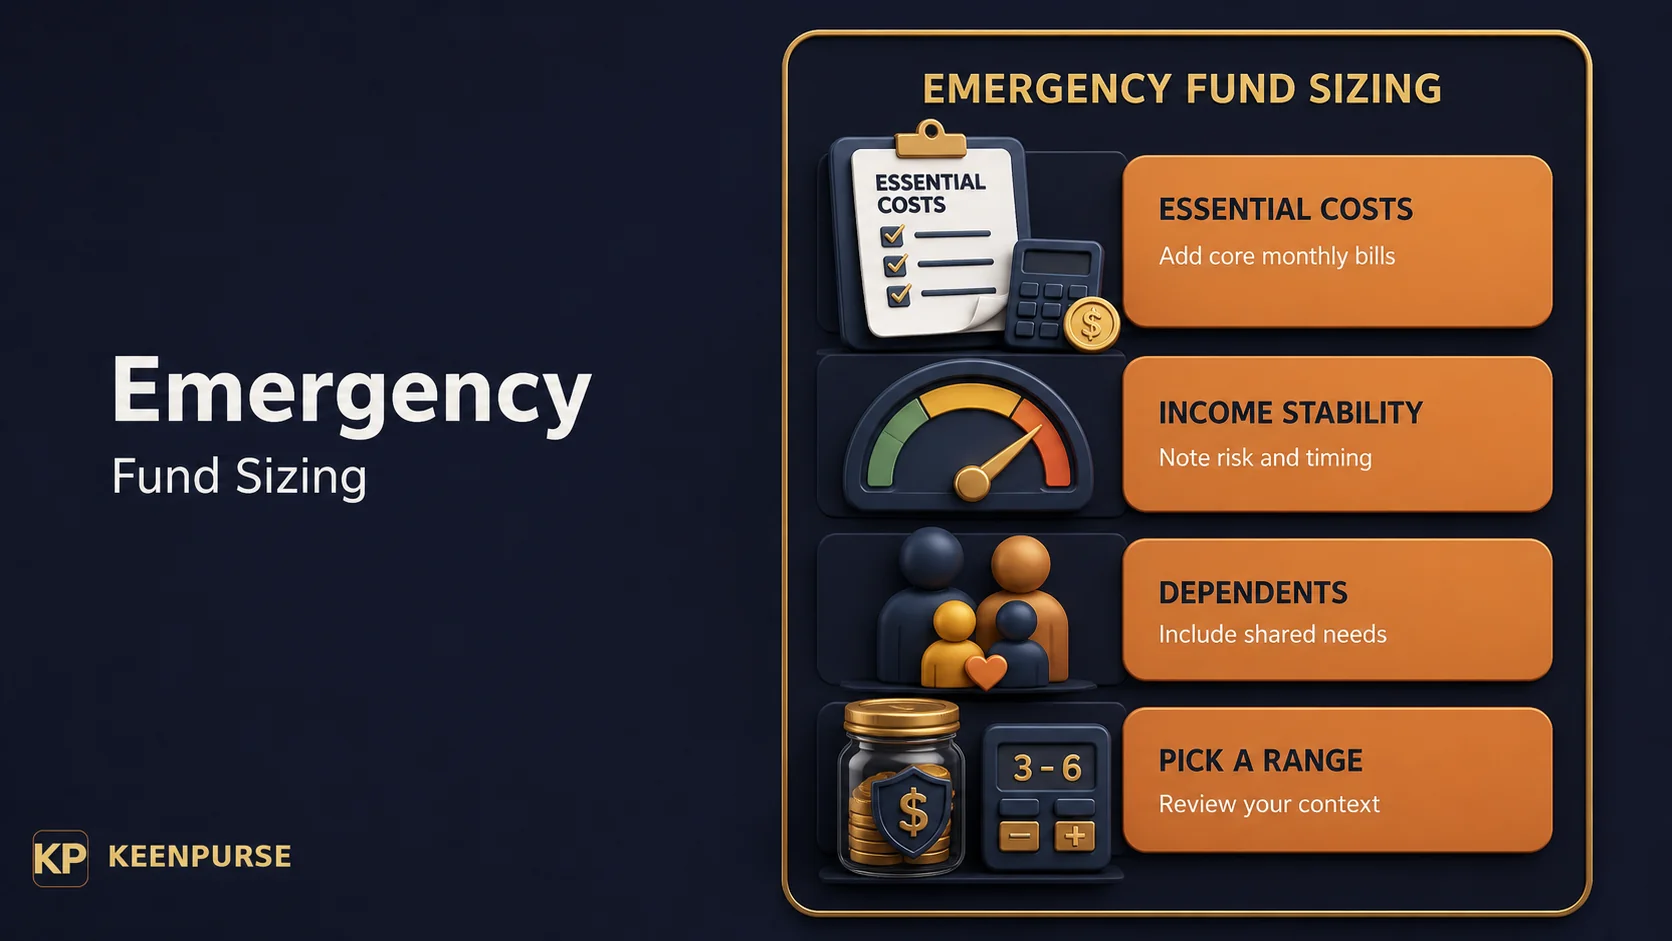
None of these rows alone sets your number. They are *levers* you pull in combination to land yourself inside the 3–6-month range — or, in some cases, to justify going modestly above or below it.
The one thing you should never do is pick a figure because it sounds tidy; size it to your own costs, as both authorities advise. Revisit how much should I have in an emergency fund whenever your costs or income stability changes.
What stretches you toward 6 months (or more)
These are judgment inputs, not rules: The useful question is how much should I have in an emergency fund before the next unplanned expense.
- Your income is unstable or irregular. If you are self-employed, on commission, paid by contract, or in a seasonal role, a bigger buffer absorbs months where income is thin or absent. The CFPB’s strategies are built for fluctuating pay, and one-time inflows like a tax refund are a common way to start.
- You are the only earner. There is no second paycheck in the household to bridge a gap.
- You support dependents. Childcare, tuition, or supporting family members add costs that a reserve may need to cover.
- Your insurance has large deductibles. A single claim could present a large bill; the fund doubles as the buffer between you and that deduction.
- Your essential costs are high. A higher baseline simply needs more months-worth to feel safe.
What pulls you toward 3 months (or less)
Symmetrically, some situations make a smaller reserve defensible: In practice, how much should I have in an emergency fund depends on the risks this plan needs to cover.
- Stable, predictable salary with an employer and benefits you can reasonably expect to rely on.
- Dual income where either wage could largely cover the essentials.
- Low fixed costs and low (or zero) deductibles.
- Other liquid buffers that already exist — for example, the continuity from a sinking fund is not an emergency fund, but an existing accessible reserve can change how large your separate emergency buffer needs to be.
The closer you land to steady, simple, low-cost, dual-income circumstances, the more comfortable it can be to stay near the bottom of the range.
Please note: even then the reserve exists to be a reserve — it is not money to invest for growth. Use this step to decide how much should I have in an emergency fund for your own next period.
Emergency fund vs. sinking fund: know which bucket is which
A common source of sizing confusion is the difference between an emergency fund and a sinking fund. They are not the same reserve: That keeps how much should I have in an emergency fund tied to your actual essentials, not a generic promise.
- An emergency fund covers *unplanned* shocks — job loss, a sudden medical bill, an emergency repair you did not see coming.
- A sinking fund holds money for *expected, dated* expenses — holiday spending, a car that will need tires, tuition due at a known date.
Because the two fund different things, they should not be mentally merged when you size your emergency number. You might keep a sinking fund for a predictable car repair *and* an emergency fund for the shock you cannot schedule.
The mechanics of building a dated-expense account are covered in how to create a sinking fund. Revisit how much should I have in an emergency fund whenever your costs or income stability changes.
Where should the emergency fund sit?
The emergency fund is for speed and safety, not growth. That usually means a separate, liquid account you can reach quickly without penalty — not money locked away where withdrawing it is costly, and not money invested in the market where its value can fall exactly when you need it.
The CFPB recommends keeping emergency savings somewhere safe, accessible, and where you’re not tempted to spend it on non-emergencies; the UK authority likewise suggests holding it in an instant-access savings account.
The practical “where to hold it” question — account types, liquidity, and how these work internationally — is covered in the dedicated article high-yield savings accounts, international, which owns account-type and rate detail. This article does not restate rates or recommend a specific product. The useful question is how much should I have in an emergency fund before the next unplanned expense.
If you keep it in the same account you spend from, it is easy to blur the line between “reserve” and “spending.” A separate bucket — even a separate account — makes the reserve easier to see and harder to dip into for non-emergencies.
In practice, how much should I have in an emergency fund depends on the risks this plan needs to cover.
This article’s boundary: the amount here, the plan in the build article
To keep the two emergency-fund articles from overlapping, this one answers the amount question and the sibling article owns the build plan. Use this step to decide how much should I have in an emergency fund for your own next period.
| Question | Where it’s answered | What that article covers |
|---|---|---|
| How much should I have? (the 3–6 month range, sizing by situation) | This article | The amount rule, essential-expense math, the sizing table, FAQs |
| How do I actually build it? (the plan) | how to build an emergency fund in 90 days | The action plan — cutting, automating, earning — and the starter-target mechanic |
If you are clear on *how much* and now want the step-by-step plan, the sibling article how to build an emergency fund in 90 days is the right doorway.
This one deliberately does not re-teach the 90-day plan; the amount article and the build article are two halves of the same job. That keeps how much should I have in an emergency fund tied to your actual essentials, not a generic promise.
How to keep the bucket growing over time
Figuring out “how much” is not a one-time answer, because your essentials and your situation drift. A few habits keep the number honest: Revisit how much should I have in an emergency fund whenever your costs or income stability changes.
- Recalculate your essential baseline whenever your life changes — a job change, a move, a new dependent, a different insurance plan.
- Fold a regular contribution into your normal budget. If you use a percentage-allocation approach like the 50/30/20 budget rule, the savings sliver is where an emergency contribution lives.
- Use a small, repeatable savings challenge to make the habit pleasant. A simple weekly-amount routine like the 52-week money challenge can build a helpful buffer by increments.
- Top the fund back up after you use it. The CFPB is explicit that if you spend your emergency savings, you should build it up again.
None of these is a promise of a particular total; they are methods for keeping a target that is actually yours in reach. The useful question is how much should I have in an emergency fund before the next unplanned expense.
Frequently Asked Questions
What is the 3-6 month rule?
The 3-to-6-month rule is the common guidance that an emergency fund should hold enough to cover roughly three to six months of your *essential* expenses. The UK authority describes it as a rule of thumb that gives a solid financial cushion; the US authority frames the amount as depending on your situation.
It is a planning anchor, not a regulatory requirement or a guaranteed amount for anyone. You size your own target inside that range using your own costs and situation. In practice, how much should I have in an emergency fund depends on the risks this plan needs to cover.
Is it 3 or 6 months?
It is a range, and where you land is a judgment, not a fixed choice. Lower fixed costs, a stable dual income, and small deductibles can make 3 months defensible; irregular income, single-earner households, dependents, or large deductibles tend to pull toward 6 months or more.
Both authorities treat the figure as guidance to adapt, not a fixed amount. Use this step to decide how much should I have in an emergency fund for your own next period.
Should my emergency fund sit in a checking account?
Not necessarily, and it should not be money you can casually spend. The requirement is liquidity and separation — funds you can reach quickly without penalty. The CFPB recommends keeping emergency savings safe, accessible, and out of temptation; the UK authority suggests an instant-access savings account.
The account-type and rate detail is the separate article high-yield savings accounts, international. An emergency fund is normally not invested in the market, because its value should not swing down when you need to withdraw it. That keeps how much should I have in an emergency fund tied to your actual essentials, not a generic promise.
Do I include irregular income when sizing my emergency fund?
Yes — irregular income is one of the strongest reasons to lean toward the higher end of the range. If you are self-employed, on commission, contract, or seasonal, your target may need a larger buffer to smooth months where pay is thin or absent.
The CFPB’s guide explicitly assumes pay can fluctuate and tailors its starting strategies to that reality, noting one-time inflows are a common way to begin. Income volatility is a factor that pushes the multiple up rather than a separate arithmetic line. Revisit how much should I have in an emergency fund whenever your costs or income stability changes.
What if my bills exceed my emergency fund?
An emergency fund is rarely a complete substitute for income — a long unemployment stretch or a very large shock can outrun any reserve.
If your bills exceed what your fund can cover, the realistic response is layered: trim essential costs, draw on the fund deliberately, use any income support you are entitled to in your market, and rebuild as soon as you can.
The UK authority also notes that it can be cheaper in the long run to clear high-cost debts before pouring everything into savings. The fund is a buffer that buys you time, not a guarantee that no bill will ever exceed it. The useful question is how much should I have in an emergency fund before the next unplanned expense.
When do I stop growing the emergency fund?
You stop when your reserve can cover the essential-expense months you decided on, given your cost baseline and risk factors.
Do not keep inflating it at the expense of everything else; once the reserve is comfortably within your target, your savings can flow to other goals, such as retirement through a 52-week money challenge or a 50/30/20 budget rule savings bucket.
In practice, how much should I have in an emergency fund depends on the risks this plan needs to cover.
Use this step to decide how much should I have in an emergency fund for your own next period.
Sources and further reading
- [CFPB] — Consumer Financial Protection Bureau emergency-fund guide, “An essential guide to building an emergency fund,” https://www.consumerfinance.gov/an-essential-guide-to-building-an-emergency-fund/ (accessed 2026-08-19). Jurisdiction: US. Supports: emergency fund defined as a cash reserve for unplanned expenses (car/home repairs, medical bills, loss of income); “the amount you need depends on your situation”; even a small amount can provide some financial security; keep savings safe, accessible and out of temptation; if you spend it, build it back up. *The CFPB does not publish a “3–6 months” figure, so that range is cited to MoneyHelper and treated as conventional guidance only.*
- [MoneyHelper] — MoneyHelper / Money and Pensions Service (UK), “How much to save for an emergency” (also listed as “Emergency savings – how much is enough?”), https://www.moneyhelper.org.uk/en/savings/types-of-savings/emergency-savings-how-much-is-enough (content verified against a 2026-01 archive snapshot, © 2026 Money and Pensions Service; accessed 2026-08-19). Jurisdiction: UK. Supports: “rule of thumb… three to six months’ essential outgoings available in an instant access savings account”; any amount saved helps with unexpected costs; paying priority debts before saving for emergencies.
How Much Should I Have in an Emergency Fund? A Sizing Guide for Your Situation Read More »